


Which Assets Are Not Part of an Estate in Canada?
Not all assets go through your estate when you die.
Some assets are set up to transfer directly to another person, which can make the process faster and may help avoid probate fees.
Some examples of assets which do not go through your estate in Canada are jointly owned property, registered accounts, and life insurance with designated beneficiaries.
Written By Tiffany Woodfield, Financial Advisor, TEP®, CRPC®, CIM®
Summary of Key Points
- Some assets can pass directly to another person instead of going through your estate and probate.
- These assets may include jointly owned property, registered accounts and life insurance with named beneficiaries, and assets held in a trust.
- Keeping assets outside your estate can make transfers faster, reduce probate fees, and provide more privacy.
- Beneficiary names, joint ownership, and trusts must be set up properly.
- Mistakes can cause assets to enter the estate or go to the wrong person.
- Estate planning is about more than avoiding probate.
- A good plan helps control who receives your assets, when they receive them, and how they are protected.
Table of Contents
- Why Does This Matter?
- Types of Assets that Do Not Form Part of an Estate
- Use the Right Tools and Consider What Matters Most
- Case Study: Estate Planning for a Blended Family Using TODs and a Trust
- When Do Assets Still Become Part of an Estate?
- What Are the Pros and Cons of Keeping Assets Outside the Estate?
- When Should You Get Professional Estate Planning Help?
- Common Questions
Why Does This Matter?
When assets aren’t part of your estate, they don’t have to go through the formal probate process to validate your will. They can transfer directly, which saves time and money.
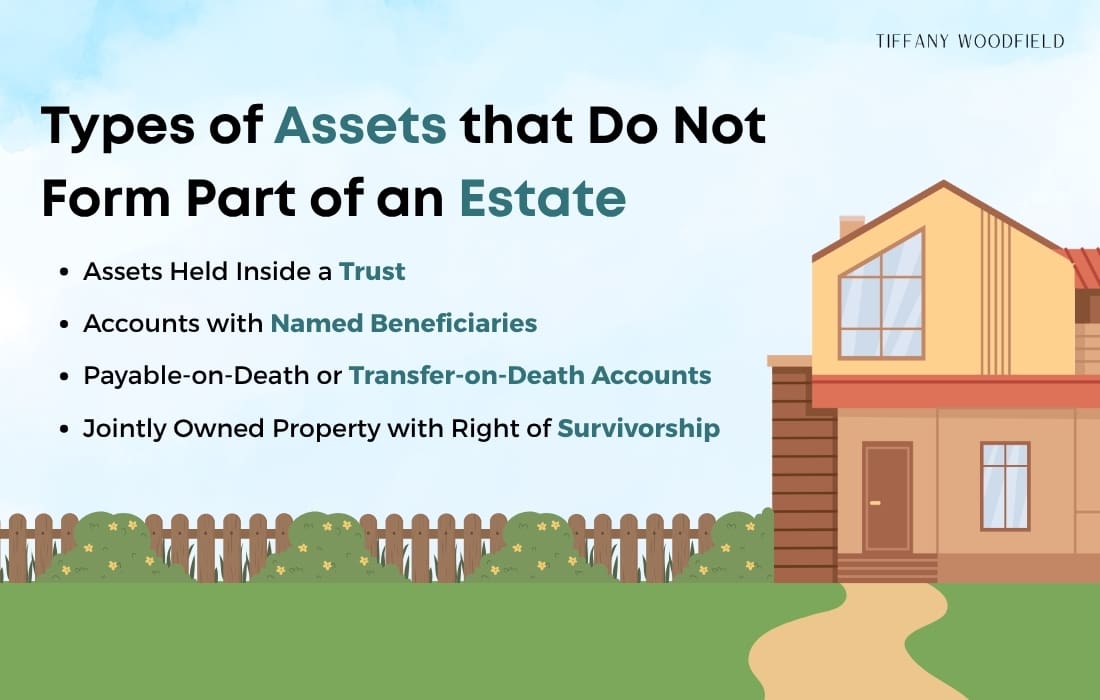
Types of Assets that Do Not Form Part of an Estate
Jointly Owned Property with Right of Survivorship
When two people own an asset jointly with a right of survivorship, the surviving owner automatically becomes the sole owner when the other person dies. For example, if Mike and Debbie have a vehicle registered under both their names. If Mike dies, Debbie automatically becomes the sole owner and bypasses probate.
Accounts with Named Beneficiaries
Accounts such as RRSPs, RRIFs, TFSAs, pensions, and life insurance allow you to name a beneficiary who will receive the asset when you pass. It is important to make sure you have designated beneficiaries on all accounts that offer this benefit.
Assets Held Inside a Trust
Assets placed in a trust are legally owned by the trust, not by the individual. Thus, when an individual dies, the assets in the trust are usually separate and don’t form part of your estate.
Payable-on-Death or Transfer-on-Death Accounts
POD and TOD accounts allow you to name a beneficiary who will receive the funds directly when you die. When set up properly, these accounts can transfer to the beneficiary without becoming part of the estate.
A payable-on-death account is used for standard bank accounts, such as checking accounts, savings accounts, and certificates of deposit.
A transfer-on-death account is used for brokerage accounts, stocks, bonds, and other investment securities.
Use the Right Tools and Consider What Matters Most
Use the available estate planning tools to make your estate transfer as smooth as possible.
While saving money through probate and administration fees is nice, remember that the probate process is there to prove the validity of your will. In other words, probate helps to make sure your wishes are followed.
I always recommend naming designated beneficiaries and reviewing these at least every couple of years. I typically don’t recommend holding all assets jointly as this can add complications. Having two owners of an asset can make things more complicated.
In addition, a trust is an excellent structure, but it isn’t right for everyone.
You need to consider what matters most to you and the potential risks that come with any decision.
Case Study: Estate Planning for a Blended Family Using TODs and a Trust
Mike* is married to Joyce. He has a stepson, Ryan, from his first marriage.
While Joyce has a daughter, Emma, who has a history of spending money quickly and struggling to manage finances.
Mike wants to make sure Joyce is financially secure if he dies first, while also ensuring that Ryan eventually receives part of his inheritance.
To achieve this, he names Ryan as the beneficiary of his RRSP and life insurance policy so those assets pass directly to Ryan and do not form part of his estate.
Mike also places some of his non-registered investments into a trust. The trust can provide income and financial support to Joyce during her lifetime, and when Joyce passes away, any remaining assets are distributed to Ryan.
Mike still uses his will to deal with assets that remain in his estate, such as personal belongings, vehicles, or other assets that were not transferred to the trust. He feels that Emma will be taken care of through Joyce.
You can see from this example that estate planning isn’t just about saving probate fees. Sometimes it’s about controlling who gets what, when they get it, and protecting the people you care about.
When Do Assets Still Become Part of an Estate?
If you don’t set up a trust properly, or if you’re missing beneficiaries on your registered accounts, or if joint ownership isn’t structured properly, your assets may still become part of your estate. This means you will have missed the opportunity to bypass probate.
What Are the Pros and Cons of Keeping Assets Outside the Estate?
Pros of Assets Bypassing the Estate
- Faster transfer of assets to loved ones after death.
- Greater privacy, as these assets may not be subject to the public probate process.
- Avoid costly probate fees and administrative expenses.
Cons of Assets Outside the Estate
- If assets are transferred to an irrevocable trust, you may lose the ability to change your mind or access those assets later.
- Outdated beneficiary designations can lead to assets going to the wrong person.
- These assets may not be distributed according to your will, which can create unintended outcomes or family disputes.
When Should You Get Professional Estate Planning Help?
Professional estate planning help becomes increasingly important as your life and finances become more complex.
A lawyer can help prepare legal documents such as Wills, Powers of Attorney, and Representation Agreements. An accountant can provide guidance on tax implications, while a financial advisor can help coordinate your overall estate strategy and ensure your assets align with your goals.
You should consider seeking a professional with experience handling situations like yours. For example, get specialized advice if you own a business, have a blended family, expect an inheritance, or have assets in more than one jurisdiction.
Remember: Even if your situation appears straightforward today, professional guidance can help identify issues before they become costly problems later.
Estate planning is not a one-time event. Life changes because people get married, divorce, or have children or grandchildren. People move, sell a business, retire or receive an inheritance, which are all good reasons to review your plan.
Common Questions
What does it mean for an asset to bypass an estate?
An asset bypasses the estate when it transfers directly to another person at death rather than passing through the deceased’s estate. This means it is transferred outside of the will and doesn’t need to go through the probate process.
How do beneficiary designations affect estate assets?
Beneficiary designations reduce estate assets because, when set up properly, the asset doesn’t form part of the deceased’s estate. Instead, the asset goes directly to the named beneficiary.
Get the Money Secrets Letter
Pop your email address in the form below to get my easy checklist and guide to manifesting and the guided audio meditation to help you get started.
You’ll also get one or two emails per month with the latest blog posts about abundance, wealth-building, manifesting, estate and legacy planning, generational wealth, and creating a fulfilling life.
Read More:
💎 Who Needs to Do Estate Planning in Canada?
💎 17 Will and Estate Planning Tips for Canadians
💎 How Is Estate Planning Beneficial to Families in Canada?
About the Author

TIFFANY WOODFIELD is a senior financial advisor, estate-planning expert, and dual-licensed portfolio manager based in Kelowna, British Columbia. She is the co-founder of SWAN Wealth Management, where she helps Canadian and cross-border families build lasting wealth, reduce tax risk, and create meaningful legacies.
As a TEP (Trust and Estate Practitioner) and portfolio manager, Tiffany works closely with successful professionals, business owners, and internationally mobile families who want to enjoy a more flexible, work-optional lifestyle. She combines deep technical expertise in wealth management with a strong focus on mindset, personal development, and purposeful decision-making.
Tiffany has been a contributor to Bloomberg TV and has been featured in major national and international publications, including The Globe and Mail and Barron’s, for her insights on retirement planning, cross-border wealth issues, and estate planning.
Professional designations:
- TEP® – Trust and Estate Practitioner
- CRPC® – Chartered Retirement Planning Counselor
- CIM® – Chartered Investment Manager
*Names have been changed to protect the identity and privacy of the individuals in this story. Please seek the advice of professionals before taking action. This case study is for educational purposes only.